












Regulatory Updates for Credit Cards: What Consumers Need to Know
The credit card industry has been a cornerstone of modern finance, providing individuals and businesses with a convenient means of making transactions.
However, with the rise of consumer debt and the complexity of credit card agreements, regulatory bodies have stepped in to implement changes aimed at enhancing consumer protection and promoting transparency.
These regulatory updates for credit cards are set to reshape the industry, affecting both cardholders and financial institutions.
In this article, we will delve into the specifics of these updates, their implications, and what they mean for the future of credit card usage.
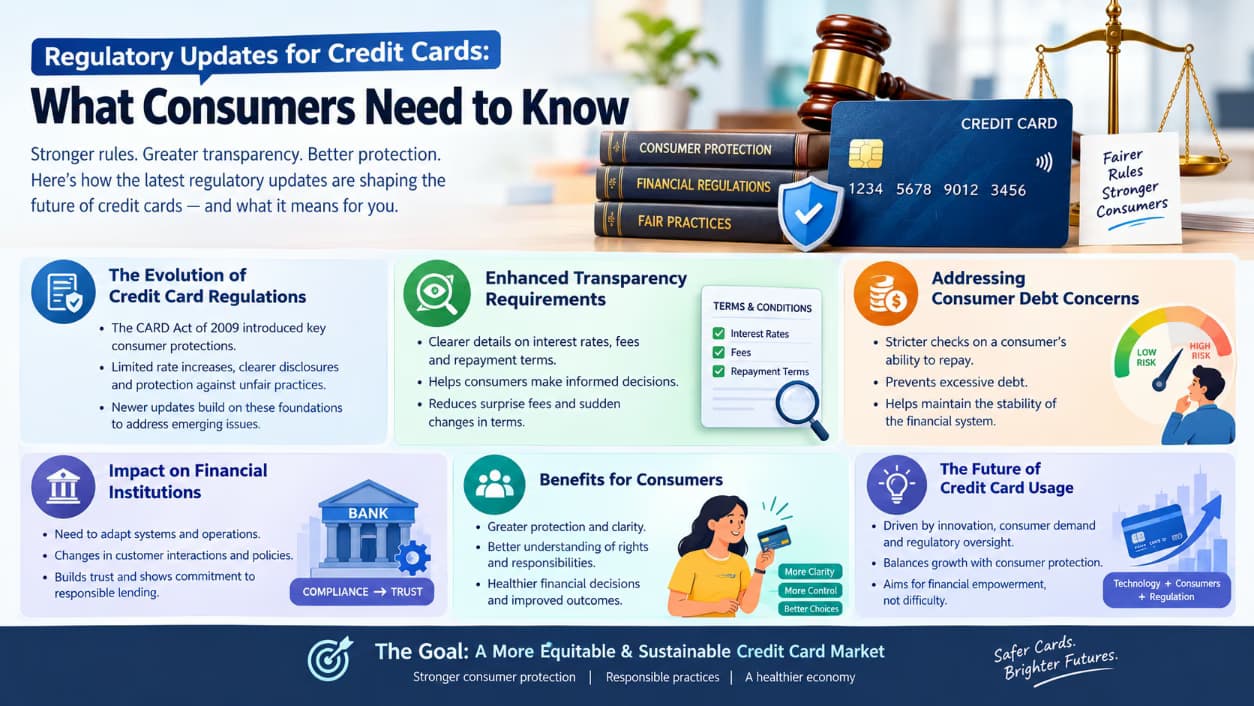
The Evolution of Credit Card Regulations
The credit card industry is not new to regulations.
Over the years, various laws and guidelines have been put in place to safeguard consumers and ensure that financial institutions operate fairly.
One of the most significant pieces of legislation in this area is the Credit Card Accountability Responsibility and Disclosure (CARD) Act of 2009.
This act introduced a range of consumer protections, including restrictions on rate increases, requirements for clearer disclosures, and protections against unfair practices.
Despite these protections, the need for further regulation has become apparent.
The latest round of regulatory updates is designed to address emerging issues and to further strengthen consumer safeguards.
Enhanced Transparency Requirements
A key aspect of the new regulations is the enhancement of transparency.
Credit card companies will be required to provide clearer and more detailed information about their terms and conditions, including interest rates, fees, and repayment terms.
This move is intended to empower consumers, enabling them to make more informed decisions about their credit card usage.
Furthermore, the updates aim to curb abusive practices, such as surprise fees and sudden changes in terms, which have been a source of frustration for many cardholders.
By introducing stricter rules on how credit card companies can alter their agreements, regulators hope to create a more stable and predictable environment for consumers.
Addressing Consumer Debt Concerns
Another significant area of focus is consumer debt.
The regulatory updates include measures designed to prevent consumers from accumulating excessive debt.
For instance, credit card companies may face stricter requirements when it comes to assessing a consumer's ability to repay, ensuring that credit is not extended to those who may struggle to meet their obligations.
This approach not only protects consumers from the risks associated with debt but also helps to maintain the stability of the financial system.
Impact on Financial Institutions
The impact of these regulatory updates will be felt across the credit card industry.
Financial institutions will need to adapt their practices to comply with the new rules, which may involve significant changes to their operations and customer interactions.
While some institutions may view these changes as burdensome, they also present an opportunity for banks and credit card companies to rebuild trust with their customers and to demonstrate their commitment to responsible lending practices.
Benefits for Consumers
For consumers, the updates offer enhanced protections and greater clarity about the terms of their credit card agreements.
By understanding their rights and responsibilities, consumers can make better choices about how they use credit, potentially leading to improved financial outcomes.
The regulatory landscape for credit cards is not static, and these updates are part of an ongoing process to balance consumer protection with the need for a vibrant and competitive financial sector.
As the industry evolves, it is likely that further changes will be introduced, reflecting new challenges and opportunities.
The Future of Credit Card Usage
In conclusion, the latest regulatory updates for credit cards mark an important step forward in the quest for greater transparency, consumer protection, and financial stability.
While they present challenges for financial institutions, they also offer a chance for the industry to redefine its relationship with consumers and to play a more positive role in facilitating economic activity.
As the credit card industry continues to adapt to these changes, it is clear that the future of credit card usage will be shaped by a combination of technological innovation, consumer demand, and regulatory oversight.
The interplay between these factors will determine not only how credit cards are used but also the broader implications for personal finance and the economy as a whole.
Ultimately, the goal of these regulatory updates is to ensure that credit cards serve as a tool for financial empowerment, rather than a source of difficulty, for those who use them.
By promoting responsible practices and safeguarding consumer interests, regulators aim to create a more equitable and sustainable credit card market, one that benefits both individuals and the economy at large.