













India’s most detailed credit card reviews
Best Credit Cards in India ThatPay You Back
We compare fees, reward rates and real-world perks across every major Indian bank — so you can stop guessing and pick the card that fits how you actually spend.
Platinum
•••• •••• •••• 4289
Guruji MemberCG
₹18,400rewards / year
5% backon groceries
12 visitsairport lounge
Start here
Browse by what you spend on
Every category is ranked on real reward value, not on who pays us the most.
Editor's picks
View allFeatured credit cards
The cards our team keeps recommending this month, across every spending style.

How it works
Three steps to a better card
No forms, no sales calls, no credit check to browse.
By bank
View allMajor credit card issuers
Already bank with someone? Start with their line-up.




Just added
View allLatest credit cards
Newly launched and recently refreshed cards, reviewed as soon as the terms go live.


Maximise points
View allBest rewards credit cards
Highest earn rates on everyday categories, valued at realistic redemption rates.
Money back
View allBest cashback credit cards
Simple, direct savings with no points to track and nothing to redeem.
Our promise
Why you can trust these rankings
We make money when readers apply through us — so the only way this works long term is if our recommendations are actually good.
Miles & lounges
View allBest travel credit cards
Lounge access, low forex markup and airline transfer partners that are actually worth using.
At the pump
View allBest fuel credit cards
Surcharge waivers and bonus points that pay off if you drive most days.

Still weighing up two cards?
Put them side by side and see the fees, reward rates and perks in one table — no guesswork, no sales pitch.
Editorial Guide & Insights
The Comprehensive Guide to Credit Cards in India (2026)
Choosing the right credit card isn't about collecting the flashiest piece of plastic—it's about making your existing monthly expenses work for you. Whether you spend primarily on groceries, utility bills, weekend dining, or international flights, the Indian credit card ecosystem has matured rapidly, offering tailored products for every spending profile.
At CardsGuruji, our editorial team analyzes credit card terms, reward point conversion rates, fee structures, and milestone benefits so you can cut through the marketing noise and pick the card that genuinely adds money back into your wallet.
Comparison Matrix
Credit Card Categories Comparison
Compare average reward returns, target spending styles, and find the top categories available in India.
| Category | Best Suited For | Average Returns | Key Highlight | Explore |
|---|---|---|---|---|
Cashback Cards | Everyday online shoppers, grocery & food delivery apps | 1% to 5% direct cashback | Direct statement credit with zero reward catalogue fuss | Explore Cashback |
Rewards Cards | High-volume spenders who hit quarterly & annual milestones | 1.5% to 8% in points/vouchers | Multiplied value on brand vouchers & milestone bonuses | Explore Rewards |
Travel & Air Miles | Frequent flyers, international holidaymakers & road warriors | 4% to 12% in flights & stays | Complimentary airport lounge access & low forex markup | Explore Travel |
Lifetime Free (LTF) | Beginners, backup cardholders & low-frequency spenders | 0.5% to 2% basic value | Zero joining & zero annual fees without spend conditions | Explore Lifetime Free |
Fuel Surcharge Cards | Daily vehicle commuters & highway road-trippers | 3% to 7% fuel points | 1% fuel surcharge waiver at partner pumps (BPCL, IOCL, HPCL) | Explore Fuel |
RuPay UPI Cards | Street-vendor payments, local merchants & chai/grocery QR scans | 0.5% to 2% on merchant UPI | Links directly to Google Pay, PhonePe & Paytm with no POS machine needed | Explore RuPay |
Actionable Rules
Smart Credit Card Rules Every Indian Should Follow
Master these 4 strategic financial practices to maximize rewards and avoid costly bank charges.
Credit Score Health
The 30% Credit Utilization Ratio (CUR) Rule
Credit bureaus like CIBIL and Experian closely track how much of your sanctioned limit you use each billing cycle. Even if you pay in full every month, exceeding 30% of your total credit limit signals credit hunger and can temporarily lower your CIBIL score. If your monthly expenses are high, consider requesting a limit upgrade or splitting purchases across two cards.
Financial Warning
The Dangerous 'Minimum Amount Due' Trap
Paying only the Minimum Amount Due (usually 5% of total balance) avoids late payment fees, but immediately revokes the interest-free grace period on your entire outstanding balance. Finance charges of 3.5% to 3.75% per month (42% to 45% APR annualized) start compounding daily on all existing and new purchases. Always clear the Total Amount Due by the due date.
Travel Policy Alert
Spend-Based Airport Lounge Access in 2026
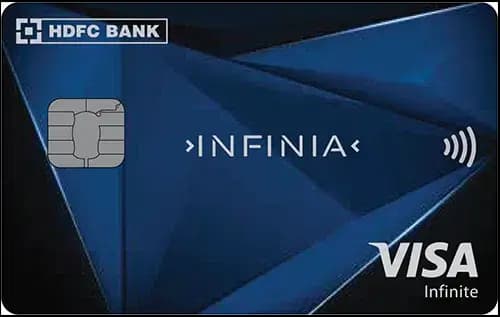
Most Indian banks (including ICICI, HDFC, and Axis) have phased out unconditional complimentary lounge visits on entry-level and mid-tier cards. To unlock lounge vouchers, cardholders must typically spend ₹10,000 to ₹50,000 in the preceding calendar quarter. Ultra-premium cards (e.g., Infinia, Magnus, Emeralde) continue to offer unrestricted lounge privileges.
Digital Payments
RuPay on UPI: What You Need to Know
RuPay credit cards allow you to pay merchants via any UPI QR code without swiping physical plastic. However, peer-to-peer (P2P) transfers to friends, family, or bank accounts are strictly blocked. Merchant payments (P2M) earn standard reward points, though tiny roadside micro-merchants below ₹2,000 are occasionally exempt from MDR-dependent rewards.
Fee Transparency
Understanding Credit Card Fees & Smart Waivers
Credit cards come with transparent fee schedules. Here is what typical charges look like in India and how you can avoid them.
| Fee Type | Typical Market Range | How to Avoid or Waive | Pro Tip |
|---|---|---|---|
| Joining & Annual Fee | ₹499 to ₹12,500 + GST | Achieve the annual milestone spend (typically ₹1L to ₹5L/year) or ask customer care before renewal | Many banks proactively waive annual fees if you threaten to cancel an active, on-time card. |
| Forex Markup Fee | 1.99% to 3.5% + 18% GST | Use dedicated zero-forex cards (like Scapia, AU Ixigo, or RBL World Safari) for overseas travel | Always select the local foreign currency at POS/online checkouts—never choose INR to avoid dynamic currency conversion (DCC) extra charges. |
| ATM Cash Advance Fee | 2.5% of withdrawn amount (min. ₹500) | Cannot be waived; interest starts accruing from the exact hour of ATM withdrawal | Never withdraw cash using a credit card except in extreme emergencies. Use your debit card instead. |
| Finance / APR Charges | 3.5% to 3.75% per month (42% to 45% APR) | Always pay 100% of the Total Amount Due before the bill payment deadline | Set up auto-debit for the full statement balance to eliminate the risk of missing payment due dates. |
| Fuel Surcharge | 1% of fuel transaction value | Available on transactions between ₹400 and ₹4,000 on virtually all co-branded and premium cards | The 18% GST charged on the 1% surcharge is non-refundable by government regulation. |
CIBIL Score Guide
CIBIL Score Ranges: General Guidance
A credit score is one part of an issuer's independent eligibility assessment.
| CIBIL Score | General Guidance |
|---|---|
| 750+ | Generally a stronger credit profile. |
| 700–749 | Approval depends on issuer criteria and financial profile. |
| 650–699 | Some issuers may apply more restrictive eligibility criteria. |
| Below 650 | Approval may be difficult; secured credit cards may be worth exploring. |
FAQs about Common Credit Card
Real answers to common queries regarding rewards, cashback, credit health, and applications in India.
Cashback cards credit direct monetary savings back to your monthly statement, effectively lowering your bill. For example, a 5% cashback card on a ₹10,000 purchase simply deducts ₹500 from your bill. Rewards cards issue points that must be accumulated and redeemed via the bank's portal for brand vouchers, merchandise, flight tickets, or hotel stays. Rewards cards often offer higher peak redemption value if you learn their transfer partner systems, whereas cashback cards provide guaranteed, zero-friction simplicity.
Yes. If you are a student, freelancer, homemaker, or newly self-employed with no salary slips or ITR records, you can obtain a secured credit card backed by a Fixed Deposit (FD). Banks like Kotak, IDFC FIRST, Axis, and OneCard offer 80% to 90% of your fixed deposit amount as your credit limit. Using an FD-backed card responsibly for 6 to 12 months builds your CIBIL score from scratch, making you eligible for unsecured cards later.
The interest-free period ranges between 20 to 50 days depending on when you make a transaction in your 30-day billing cycle. A purchase made on Day 1 of your cycle gets the full 30 days of the cycle plus the 20-day payment grace window (total 50 days). A purchase made on Day 29 gets only 21 days. If you consistently pay your full bill on time, you never pay a single rupee in interest.
No. Browsing platforms like CardsGuruji or checking your eligibility through soft inquiries does not impact your credit score in any way. Only when you officially submit a formal credit card application to a bank will the bank trigger a 'Hard Inquiry' on your credit report. A single hard pull drops your score by a negligible 2 to 5 points, which recovers within a couple of months.
Use CardsGuruji's side-by-side comparison tool to evaluate cards on joining perks, annual fees, spend waiver thresholds, reward rates on specific categories, and airport lounge access. Comparing cards ensures you don't end up paying for perks you won't actually utilize.
Absolutely. Most seasoned cardholders use a 2-card or 3-card wallet strategy: one dedicated high-cashback card for online groceries, food delivery, and bills (e.g., 5% return), one RuPay card for offline daily UPI payments, and one travel card for lounge access and zero/low forex charges. Just ensure you never spend beyond your means and maintain auto-debit payments on all cards.
Popular Categories & Issuer Directories
Editorial Disclaimer: CardsGuruji is an independent financial comparison platform. We independently review credit cards based on genuine benefits, reward valuations, and terms. Bank policies, interest rates, reward schemes, and lounge access rules are subject to change by issuing banks. Please review the official Most Important Terms and Conditions (MITC) on the respective issuer's website before applying.