Credit Card Blogs & Guides

Latest insights, expert guides, and news from the world of credit cards to help you make smarter financial decisions.

Showing 8 Blogs

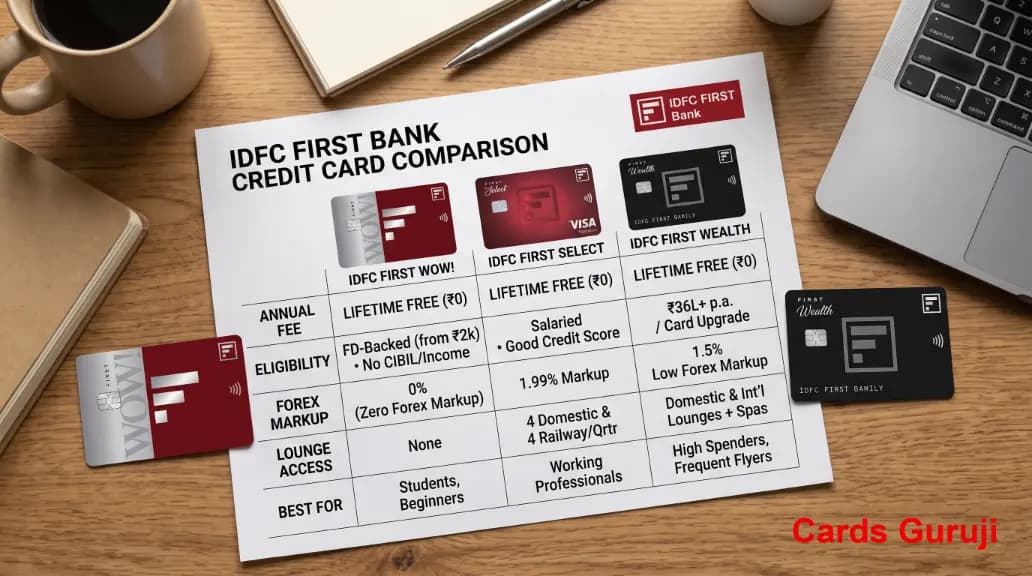
IDFC FIRST Bank Credit Cards 2026 Comparison: WOW vs Select vs Wealth—Fees, Rewards, Lounge, Best Picks
Comparision23 Oct 2026, 06:30 pm

IDFC FIRST Bank Credit Cards 2026 Comparison: WOW vs Select vs Wealth—Fees, Rewards, Lounge, Best Picks

Tired of hidden credit card fees and expiring reward points? IDFC First Bank is shaking up the market with their genuinely Lifetime Free credit cards, zero-interest ATM cash withdrawals, and never-expiring rewards. In this ultimate guide, we break down the core benefits of IDFC cards and compare the popular WOW, Select, and Wealth tiers so you can decide which one actually deserves a spot in your wallet.
Ruby
Ruby
Read Blog→
Check IndusInd Credit Card Application Status & Login Guide
Guide23 Oct 2026, 06:30 pm

Check IndusInd Credit Card Application Status & Login Guide

Navigating your new credit card shouldn't be a hassle. This quick, step-by-step guide breaks down exactly how to track your IndusInd Bank credit card application status in real-time and securely set up your online login. Save time and take full control of your finances without waiting in long customer service queues.

Devender Sharma
Devender Sharma
Read Blog→
Decoding the 2026 Festive Tech Squeeze: Why Amazon and Flipkart are Breaking Sales Records Despite Price Hikes
Shopping9 Oct 2026, 06:30 pm

Decoding the 2026 Festive Tech Squeeze: Why Amazon and Flipkart are Breaking Sales Records Despite Price Hikes

Despite recent price hikes in the tech sector, Amazon and Flipkart are breaking sales records in 2026. Discover how smart shoppers are bypassing inflated costs using premium credit card offers, extended EMIs, and strategic financing to score genuine electronics deals this festive season.

Ruby
Ruby
Read Blog→
The "Spend-Gating" Era: How to Actually Keep Your Airport Lounge Access in 2026
Travel 27 Sept 2026, 06:30 pm

The "Spend-Gating" Era: How to Actually Keep Your Airport Lounge Access in 2026

Free airport lounge access on Indian credit cards is officially over. Discover how banks introduced quarterly spend-gating in 2026, and learn practical strategies to hit spend thresholds and protect your travel perks.

Devender Sharma
Devender Sharma
Read Blog→
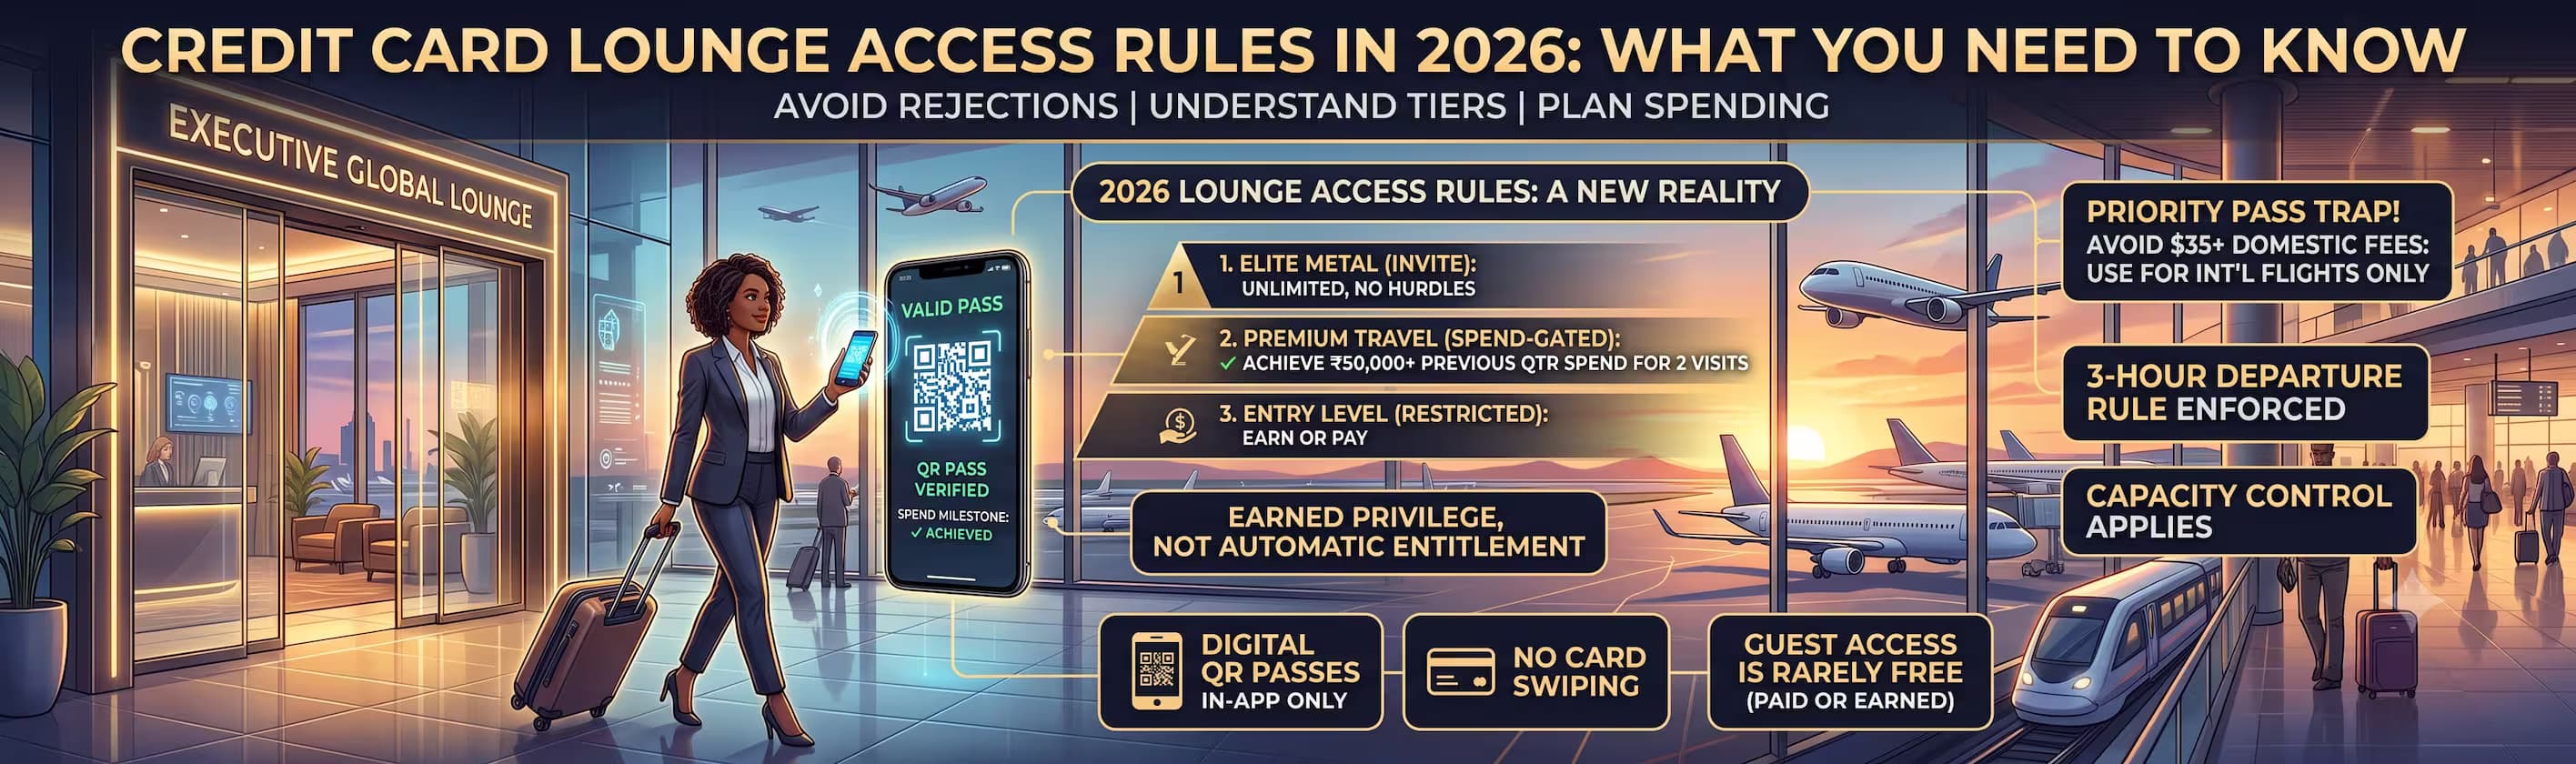
Credit Card Lounge Access Rules in 2026: What You Need to Know
Trevel25 Sept 2026, 06:30 pm

Credit Card Lounge Access Rules in 2026: What You Need to Know

Airport lounge access is changing in 2026. Learn about minimum spending requirements, lounge visit limits, guest charges, domestic and international access, and the key rules to check before your next flight.

Devender Sharma
Devender Sharma
Read Blog→
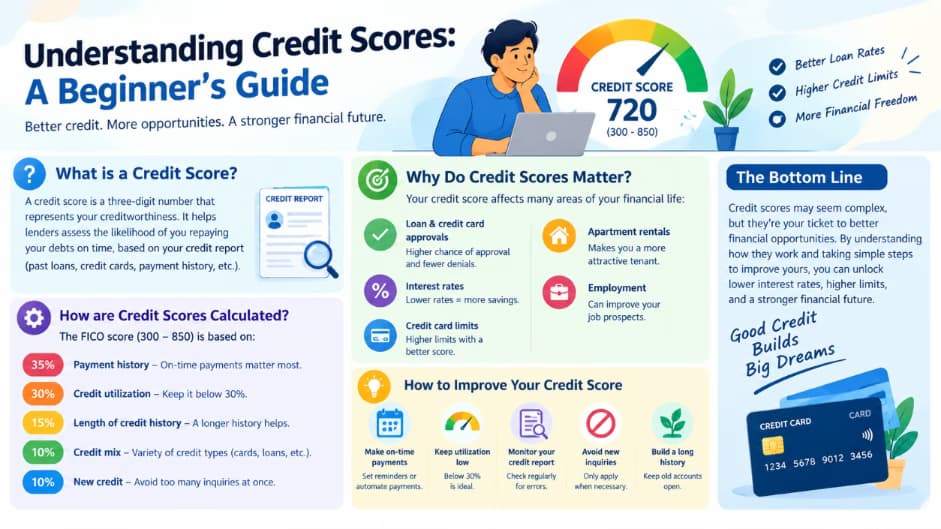
Beginner’s Guide to Credit Scores: What They Are, Why They Matter, and How to Improve
guide23 May 2026, 06:30 pm

Beginner’s Guide to Credit Scores: What They Are, Why They Matter, and How to Improve

Unpack how credit scores work and how they impact your financial future. Follow simple steps to check your history, fix errors, and improve your rating today.

Ruby
Ruby
Read Blog→
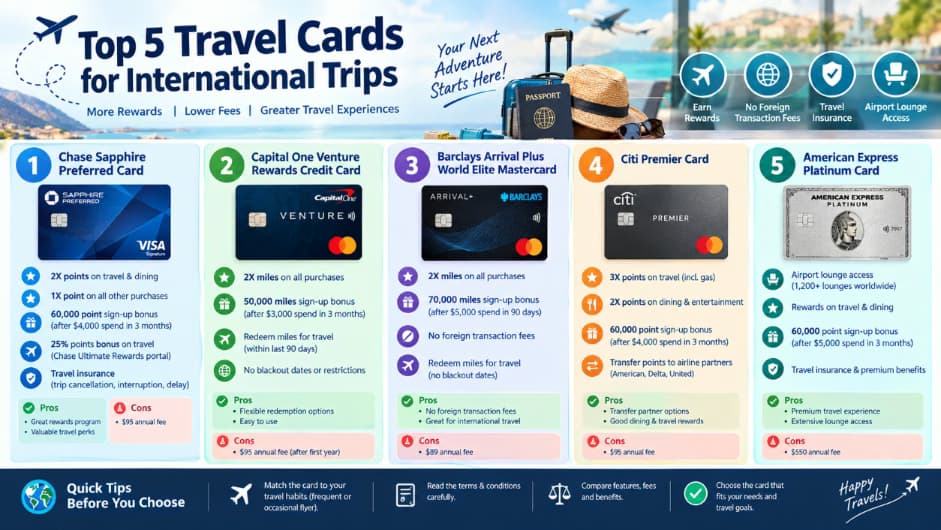
No Foreign Fees, Big Rewards: Compare 2026’s Top 5 Travel Credit Cards Today
travel23 May 2026, 06:30 pm

No Foreign Fees, Big Rewards: Compare 2026’s Top 5 Travel Credit Cards Today

Discover the top travel cards for international trips. Maximize your rewards, enjoy premium airport lounge access, and save big with zero foreign fees.

Ruby
Ruby
Read Blog→
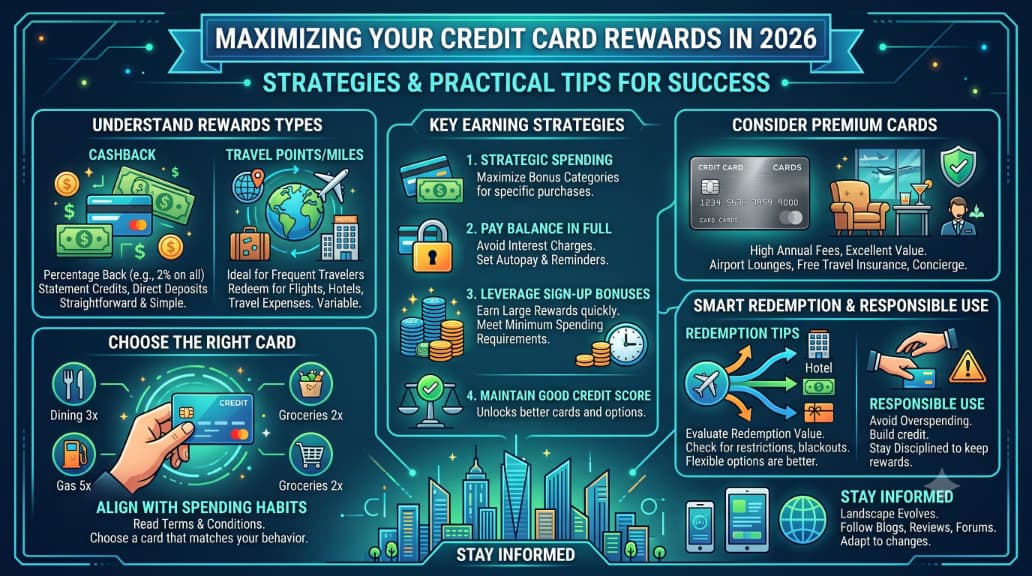
11 High-ROI Credit Card Reward Tactics for 2026 (Stop Leaving Points on the Table)
guide23 May 2026, 06:30 pm

11 High-ROI Credit Card Reward Tactics for 2026 (Stop Leaving Points on the Table)

Supercharge your wallet and maximize your credit card rewards in 2026. Explore top methods to leverage air miles, cash back, and elite hotel loyalty perks.

Ruby
Ruby
Read Blog→
Credit Card Knowledge

Credit Card Guides & Tips FAQs

Common questions about maximizing reward points, fee waivers, airport lounge rules, and choosing the right card.

For first-time applicants and beginners, lifetime free (LTF) credit cards with straightforward reward structures are ideal. Top choices include the Amazon Pay ICICI Bank Credit Card (flat 5% for Prime members with zero annual fee) and the Kotak 811 Super.Money card. Applicants with no credit history or a low CIBIL score can start with an FD-backed secured card like IDFC FIRST WOW to establish an unblemished credit record within 6 to 12 months without paying recurring annual fees.

Cashback cards credit monetary savings directly against your monthly statement balance (e.g., 5% on Flipkart or Amazon), providing guaranteed ₹1 for ₹1 value with zero redemption fees. In contrast, reward point cards award points per ₹100 or ₹150 spent, which can yield a higher effective return (typically 5% to 15%) when transferred to airline frequent flyer programs (Air India Flying Returns, Singapore KrisFlyer) or luxury hotel loyalty tiers, but require active tracking to avoid catalog devaluations and point expiry.

There is no universal CIBIL score cutoff for credit card approval. Each issuer sets criteria for each card and considers the wider financial profile, including income, employment, existing obligations and repayment history. Check the issuer's current eligibility terms; a credit score alone does not guarantee approval.

Most Indian credit cards waive the upcoming renewal fee if your cumulative retail spending reaches an annual milestone (typically ₹1 Lakh for entry cards, ₹3 to ₹5 Lakhs for premium cards). However, transactions made for rent payments, wallet top-ups (Paytm, Mobikwik), government taxes, school fees, and purchases converted into EMIs are almost universally excluded from fee-waiver milestone calculations. Always check your card's Schedule of Charges to track eligible spends.

RuPay credit cards issued by Indian banks can be linked directly to UPI applications (Google Pay, PhonePe, Paytm, BHIM) to make merchant scan-and-pay transactions. Spends up to ₹2,000 at small merchants carry zero convenience charges for cardholders and enjoy the standard 20 to 50 days interest-free credit period. This allows users to earn reward points or cashback on daily grocery, fuel, and neighborhood store purchases.

Major Indian card issuers (including ICICI Bank, HDFC Bank, Axis Bank, and SBI Card) have transitioned from unconditional complimentary lounge access to spend-linked eligibility. Mid-tier cards now require cardholders to spend ₹10,000 to ₹50,000 in eligible retail purchases in the preceding calendar quarter to unlock complimentary domestic lounge passes for the subsequent quarter. Super-premium cards (such as HDFC Infinia or Axis Magnus) remain among the few exceptions offering spend-free unlimited lounge visits.

When spending in foreign currencies online or overseas, standard Indian credit cards levy a foreign currency markup fee of 3.5% + 18% GST (effective ~4.13%). Dedicated zero-forex or low-forex credit cards (charging 0% to 1.99%) can save international travelers ₹3,000 to ₹4,000 for every ₹1 Lakh spent abroad. Additionally, cardholders should always choose to be billed in the local destination currency rather than INR to avoid inflated Dynamic Currency Conversion (DCC) charges.

Yes. Holding 2 to 3 complementary credit cards across different issuers (such as HDFC, SBI, and ICICI) expands your total aggregate credit limit. Because credit bureaus calculate your Credit Utilization Ratio (CUR) across all active cards, a higher overall limit makes it easier to keep total utilization below 30%, which directly boosts your CIBIL score while allowing you to capture merchant bank sale discounts across multiple platforms.

Paying only the Minimum Amount Due (typically 5% of your statement total) avoids late payment penalties and bureau default flags, but immediately revokes your interest-free grace period. The remaining 95% balance plus every new swipe incurs finance charges of 3.49% to 3.75% per month (42% to 45% APR) calculated from the transaction date until the entire balance is cleared in full. Paying the Total Amount Due is essential to avoid revolving debt traps.

Indian banks frequently exclude the following Merchant Category Codes (MCCs) from earning base and accelerated reward points: residential and commercial rent payments, wallet reloads, fuel pump transactions, government tax filings, utility bill payments through government portals, and transactions converted into monthly EMIs. Reviewing your card's monthly exclusion list ensures you don't miss expected returns on major spends.