












Best Dining Credit Cards in India — November 2026 [Page 4]
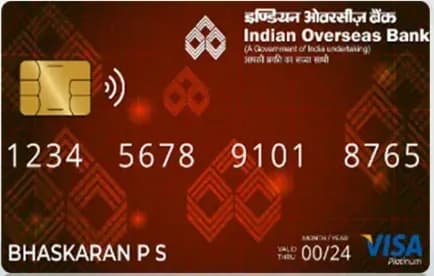
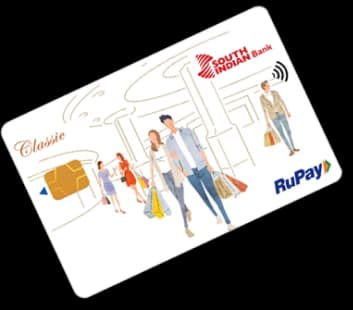
You are currently browsing Page 4 of our complete dining credit card guide, offering an in-depth archive of specialized, regional, and niche credit cards available in India for 2026. Every card featured across our directory undergoes rigorous editorial review by CardsGuruji to ensure all fee schedules, reward multipliers, milestone criteria, and terms are fully verified and up to date. Leading issuers represented here, such as Indian Overseas Bank, South Indian Bank, UCO Bank, Jammu & Kashmir Bank, provide diverse products—including IOB Visa Platinum Credit Card, IOB Visa Classic Credit Card, South Indian Bank Classic Credit Card—tailored for specialized consumer needs, unique merchant partnerships, and targeted banking relationships.
When comparing cards further in our directory, pay close attention to the card's specific interest rate (APR), foreign currency markup fees, and annual fee waiver rules. If you maintain an existing savings or salary account with the issuing bank, you may be eligible for pre-approved terms, reduced documentation, or fee waivers. Additionally, keeping your overall credit utilization ratio below 30% across all active credit cards ensures your CIBIL score remains strong while you explore new card privileges.
Evaluating cards across later pages of our directory also uncovers specialized co-branded products that deliver targeted value on specific airlines, regional retailers, or fueling networks. Use the interactive summary table below to review verified annual fees, joining fees, issuing institutions, and editorial ratings for all cards listed on this page, allowing you to make an informed, confident financial decision.
Dining Credit Cards on This Page — (2026) — Verified fees and ratings. Always verify the latest terms and conditions on the official issuing bank portal before applying.
| # | Card Name | Bank | Annual Fee | Joining Fee | Rating |
|---|---|---|---|---|---|
| 1 | IOB Visa Platinum Credit Card | Indian Overseas Bank | ₹ 500 | — | — |
| 2 | IOB Visa Classic Credit Card | Indian Overseas Bank | Lifetime Free | — | — |
| 3 | South Indian Bank Classic Credit Card | South Indian Bank | ₹ 500 | — | — |
| 4 | UCO Bank SBI Card ELITE | UCO Bank | ₹ 4,999 | — | — |
| 5 | UCO Bank SimplySAVE SBI Card | UCO Bank | ₹ 499 | — | — |
| 6 | South Indian Bank Platinum Credit Card | South Indian Bank | ₹ 500 | — | — |
| 7 | J&K Bank Platinum Credit Card | Jammu & Kashmir Bank | ₹ 500 | — | — |
| 8 | Dhanlaxmi Bank Platinum Credit Card | — | ₹ 1,000 | — | — |
Browse 39 dining credit cards — page 4 of 5


FAQs About Dining Credit Cards in India (2026) — Page 4
Helpful answers and expert guidance about choosing, maximizing rewards, and applying for dining credit cards in India.
Your billing cycle is a recurring 30-day window during which all card transactions are recorded. At the end of the cycle, your statement is generated with a payment due date approximately 15 to 20 days later. Under RBI rules, you have the flexibility to customize your billing cycle date once to align with your salary date.
Yes. Reserve Bank of India (RBI) guidelines mandate that cardholders can modify their billing cycle and payment due date at least once through mobile banking, internet banking, or customer support to match their monthly cash flow.
If you spot an unauthorized or incorrect charge, report it to your issuing bank within 30 days. The bank will issue a temporary credit while raising a formal dispute (chargeback) with the merchant's payment processor under Visa, Mastercard, or RuPay rules.
Immediately block the card via your mobile banking app or IVR customer helpline. Under RBI zero-liability guidelines, once you notify the bank of card loss or compromise, you carry zero financial liability for any subsequent fraudulent transactions.
On many cards, reward points remain valid for 2 to 3 years from the date of earning, after which unused points lapse. Some banks (like IDFC FIRST Bank) and direct cashback cards offer points and cashback that never expire for life.
Yes, provided international usage is enabled in your card controls via netbanking. Check foreign currency markup fees before spending abroad, and ensure SMS/email roaming is active to receive transaction OTPs.
The Minimum Amount Due is typically calculated as 5% of the total outstanding balance, plus all applicable taxes (GST), EMI installments, and any overdue amounts. Paying only the MAD prevents late fees but incurs interest on the remainder.
You can submit a card closure request via mobile banking, email, or customer care. Under RBI rules, banks must process closure requests within 7 business days, provided all outstanding dues and pending EMIs are fully settled.
Closing a card can slightly lower your CIBIL score if it was one of your oldest credit lines (reducing your average age of accounts) or if it significantly reduces your total available credit limit (raising your credit utilization ratio).
Log in to your bank's reward portal (such as HDFC SmartBuy, SBI Rewardz, or Axis EDGE REWARDS) to redeem points for airline tickets, hotel stays, shopping gift cards, or statement credit against your card bill.