













Best Entry Level Credit Cards in India — November 2026 [Page 2]
Page 2 of our entry level credit card directory showcases an expanded range of specialized, mid-tier, and co-branded credit cards engineered for savvy cardholders seeking tailored rewards and competitive fee structures in 2026. While entry-level products focus on basic rewards, the cards featured on this page—issued by prominent financial leaders including Axis Bank, Kotak Mahindra Bank, City Union Bank, South Indian Bank—often feature higher milestone bonuses, partner merchant discounts on dining and entertainment, and flexible annual fee waiver thresholds. Featured options on this page, including IKEA Family Credit Card by Axis Bank, Kotak Air Credit Card, Kotak 811 Credit Card, provide excellent alternatives for optimizing specific monthly expenditure streams.
When evaluating cards on this page, take time to benchmark the effective annual return by factoring in welcome vouchers, spend milestones, and reward redemption avenues. Many mid-tier entry level cards offer welcome gift cards that fully offset the initial joining fee, while offering spend-based waivers on subsequent renewals if you cross annual spend targets of ₹1 Lakh to ₹2 Lakhs. Additionally, investigate the issuer's reward redemption flexibility, verifying whether accumulated points can be redeemed for direct statement credit, shopping gift vouchers, or airline travel miles at a favorable conversion ratio.
Eligibility for mid-tier cards varies by issuer and product. Refer to the issuer's current published criteria for official credit-score and income requirements. The summary table below details active credit cards on this page, providing annual fees, joining charges, issuing banks, and editorial ratings so you can select the best fit for your lifestyle.
Entry Level Credit Cards on This Page — (2026) — Verified fees and ratings. Always verify the latest terms and conditions on the official issuing bank portal before applying.
| # | Card Name | Bank | Annual Fee | Joining Fee | Rating |
|---|---|---|---|---|---|
| 1 | IKEA Family Credit Card by Axis Bank | Axis Bank | Lifetime Free | — | — |
| 2 | Kotak Air Credit Card | Kotak Mahindra Bank | ₹ 999 | — | — |
| 3 | Kotak 811 Credit Card | Kotak Mahindra Bank | ₹ 500 | — | — |
| 4 | Kotak 811 super.money Credit Card | Kotak Mahindra Bank | Lifetime Free | — | — |
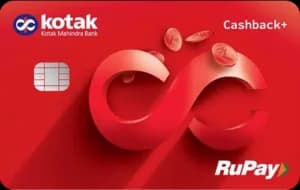
| 5 | Kotak Cashback+ Credit Card | Kotak Mahindra Bank | ₹ 750 | — | — |
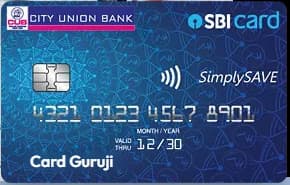
| 6 | City Union Bank Simplysave SBI Card | City Union Bank | ₹ 499 | — | — |
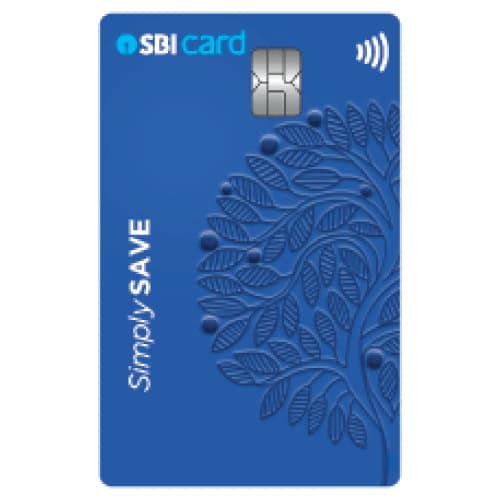
| 7 | South Indian Bank Simply Save SBI Credit Card | South Indian Bank | ₹ 499 | — | — |
| 8 | American Express SmartEarn Credit Card | American Express | ₹ 495 | — | — |
Browse 43 entry level credit cards — page 2 of 6



FAQs About Entry Level Credit Cards in India (2026) — Page 2
Helpful answers and expert guidance about choosing, maximizing rewards, and applying for entry level credit cards in India.
To maximize returns on entry level cards: (1) route your primary expenses through partner merchants that offer bonus category multipliers; (2) monitor spend milestones to unlock waiver thresholds or bonus reward vouchers; (3) pay utility bills and recharges through dedicated reward portals; and (4) always clear statement balances in full to avoid interest charges that wipe out reward savings.
Yes. Most Indian card issuers exclude wallet top-ups, rent payments, property management fees, government tax payments, and jewellery purchases from earning regular reward points or cashback. Furthermore, category rewards often carry monthly or statement-cycle caps (e.g. max ₹1,000 to ₹5,000 cashback per month). Always check the most recent MITC document of your card.
For cards with recurring annual fees, banks waive the renewal fee if you spend a specified aggregate amount during the 12-month card anniversary year. Typical waiver thresholds range from ₹50,000 for basic cards to ₹2 Lakhs–₹5 Lakhs for premium cards. Transactions made across primary and add-on cards both count towards the milestone spend.
Standard entry level credit cards levy a foreign currency markup fee of 3.5% + 18% GST on international transactions and foreign e-commerce websites. If you travel overseas frequently or shop on foreign websites, consider cards offering a reduced forex markup of 0% to 1.99% to save on cross-currency conversion costs.
Yes. Eligible transactions (usually above ₹1,500 to ₹2,500) on entry level credit cards can be converted into 3 to 24-month EMIs through your bank's mobile app or internet banking portal. Interest rates typically range from 13% to 18% per annum, and banks usually charge a nominal one-time processing fee (₹99 to ₹299 + GST).
Credit bureaus (CIBIL, Experian, Equifax) recommend keeping your monthly Credit Utilization Ratio (CUR) below 30% of your total assigned credit limit. For example, if your card limit is ₹1,00,000, keep your monthly billed statement balance under ₹30,000. Maintaining low utilization demonstrates disciplined credit habits and helps boost your credit score.
Yes. Primary cardholders can apply for supplementary or add-on entry level credit cards for family members (spouse, parents, children aged 18+). Add-on cards share the primary account's credit limit and earn reward points on consolidated spend, while allowing the primary holder to set individual transaction limits.
Missing your credit card due date incurs late payment penalties (ranging from ₹100 to ₹1,300 depending on statement balance), finance charges (3% to 3.75% per month on unpaid balances from the purchase date), and forfeiture of the interest-free grace period. Additionally, banks report defaults to CIBIL after 3 days of delay, which can negatively impact your credit score.
Yes, most entry level credit cards provide a 1% fuel surcharge waiver on transactions between ₹400 and ₹4,000 across petrol pumps nationwide (IOCL, HPCL, BPCL). The maximum waiver is usually capped between ₹100 and ₹250 per billing cycle. The GST charged on the surcharge is government-mandated and non-refundable.
To choose the best card from this page, compare: (1) your dominant monthly spending channel against the card's highest reward multiplier; (2) annual fee vs achievable milestone spend waivers; (3) partner brand discounts (Amazon, Flipkart, Swiggy, Zomato, BookMyShow); and (4) minimum income and CIBIL score requirements.