












Stop Paying Annual Fees: The Real Guide to IDFC First Credit Cards (WOW vs Select vs Wealth)
Let’s be honest for a second. The Indian credit card market is incredibly crowded right now, and it is flooded with plastic that promises you the moon, only to hit you with a massive annual fee the moment you stop paying attention to your statements.
For years, we were trained to accept that if you want good airport lounge access, decent reward points, or premium lifestyle perks, you have to pay a hefty joining fee—or spend an unreasonable amount like ₹3 Lakhs a year just to get that fee waived.
This is exactly why IDFC First Bank has been quietly stealing customers from the big traditional players over the last couple of years. If you have been searching for IDFC First Bank credit card benefits, you probably already know they do things a little differently. They decided to strip away the confusing jargon, drop the annual fees entirely, and offer a suite of cards that actually make sense for the average Indian consumer.
Here is the absolute lowdown on why these cards are getting so much hype, how the reward math actually works, and more importantly, how to figure out which one actually belongs in your wallet.
The Core IDFC Benefits: Breaking Down the Hype
Most banks reserve their genuinely good perks for the ultra-rich. IDFC flipped the script by offering a baseline of highly useful benefits across almost their entire credit card lineup. Whether you hold their entry-level card or their premium tier, you get to enjoy a specific set of foundational rules.
1. They Are Actually, Truly Lifetime Free (LTF)
There are no joining fees. There are no annual fees hidden behind a sneaky "spend ₹2 Lakhs to waive" condition. You get the card, you keep it for free, forever. You don't have to call customer care every December begging them to reverse a ₹2,999 charge. It gives you incredible peace of mind, especially if you are keeping the card just for specific category spends.
2. Interest-Free ATM Withdrawals (Yes, Really)
Normally, pulling cash from an ATM with a credit card is financial suicide. With traditional banks, cash advance fees and high interest rates start compounding from day one. IDFC is the only major player in India that lets you withdraw cash interest-free for up to 48 days. You just pay a flat ₹199 + GST per transaction fee. While we still don't recommend using credit cards at ATMs regularly, it is an absolute lifesaver in a medical or travel emergency where UPI or debit cards fail.
3. Reward Points That Don't Vanish
Have you ever tried to redeem reward points only to realize half of them expired last month? IDFC reward points never expire. You can hoard them for years. Furthermore, they don't charge you that annoying ₹99 "reward redemption fee" that almost every other major private bank in India has recently introduced. 1 Reward Point is valued at ₹0.25, and you can instantly use them to pay for your online purchases.
4. Dynamic Interest Rates That Make Sense
If you have ever carried a balance on a standard credit card, you know the interest rate (APR) is usually a brutal 36% to 42% annually. IDFC uses dynamic interest rates starting as low as 0.75% per month (which equals 9% annually). If you have a rock-solid CIBIL score and a good payment history, the bank actually rewards you with a lower APR instead of throwing everyone into the same high-risk bucket.
The Showdown: WOW vs. Select vs. Wealth
Okay, so the base perks are undeniably great. But which card should you actually apply for? Let’s cut through the marketing fluff and directly compare the three most popular options in the IDFC arsenal.
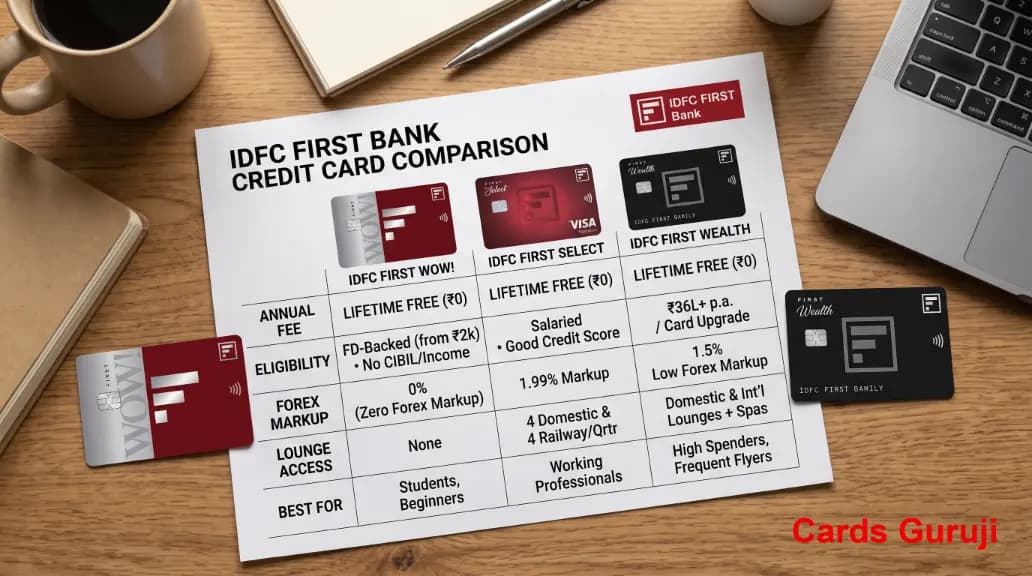
1. The Starter: IDFC FIRST WOW Credit Card
If you have a damaged credit score, or you're a college student or freelancer with zero formal credit history, getting a decent card is incredibly frustrating. The IDFC First Bank WOW credit card is the ultimate fix.
It is a secured credit card, meaning it is backed by a Fixed Deposit (starting at a minimum of just ₹2,000). Because it is secured by your own money, the bank does not care about your CIBIL score. There are no income proofs required, and approval is guaranteed.
- The Best Perk: Zero forex markup. If you are a student heading abroad for studies, a freelancer paying for foreign software subscriptions in USD, or just traveling to Dubai or Bali for a holiday, this card saves you the standard 3.5% fee most banks charge on international swipes.
- The Double Benefit: Your money isn't just sitting there. The FD backing your card continues to earn high interest (currently around 7% to 7.5% per annum) while you get 100% of the FD value as your credit limit.
- The Verdict: It is the perfect financial tool for beginners and students looking to aggressively build their CIBIL score while earning FD interest in the background.
2. The Middle Child: IDFC FIRST Select Credit Card
This is the sweet spot for most working professionals. The IDFC First Select credit card gives you a solid taste of luxury without requiring a massive executive salary. It is designed for the mid-level spender who wants a bit of everything.
- The Reward Multiplier: You earn 3X points on offline spends and 6X points on online spends. But the real magic happens when you cross ₹25,000 in a billing cycle. Everything spent above that threshold earns a massive 10X reward points.
- Lifestyle Perks: You get Buy One Get One (BOGO) movie tickets on Paytm (up to ₹250) twice a month. You also get 4 complimentary domestic railway lounge visits and 4 domestic airport lounge visits per quarter (subject to a minimum spend of ₹5,000 in the previous month).
- The Verdict: Best for the weekend traveler, the movie buff, and the young professional who wants premium lifestyle perks without paying a premium price.
3. The Heavyweight: IDFC FIRST Wealth Credit Card
This is IDFC’s premium offering. You will need a higher income bracket (usually ₹36 Lakhs+ per annum or an existing card with a ₹5 Lakh+ limit) to qualify for the IDFC First Wealth credit card. But if you do qualify, the travel and lifestyle benefits are easily some of the best in the lifetime-free category.
- Top-Tier Travel: Not only do you get standard domestic airport lounge access, but you also get complimentary international lounge visits (via the included Dreamfolks or Priority Pass network) and exclusive access to airport spas.
- Elite Perks: The card comes with a heavily reduced forex markup of just 1.5%, comprehensive travel insurance (including lost baggage and flight delay cover), and complimentary golf rounds every month based on your spends.
- The Verdict: Tailor-made for frequent flyers, HNIs, and high-spenders who want premium, status-level travel benefits wrapped in a card that costs absolutely zero to hold.
The Catch: Who Should NOT Get an IDFC Card?
No review is complete without a reality check. While IDFC cards are fantastic, they are not for everyone. You should probably look elsewhere if:
- You are a hardcore Air-Miles churner: IDFC points are great for cash-back style redemptions, but if you want to fly business class for free by converting points to Vistara or KrisFlyer miles, cards from Axis Bank, Amex, or HDFC are much better suited for you.
- You only shop on one platform: If 90% of your monthly spending happens on Amazon or Flipkart, you are better off getting the Amazon Pay ICICI or Flipkart Axis Bank credit cards, as they offer straight 5% unlimited cashback on those specific platforms.
Ready to Make the Switch? How the Process Works
If you've decided which card fits your lifestyle, getting your hands on one is entirely digital. Gone are the days of filling out 10-page paper forms and handing over physical passport copies to an agent.
Keep your Aadhaar Card and physical PAN Card handy. The process involves filling in your basic details, verifying your employment or income, and completing a quick Video KYC (V-KYC) with a bank agent through your smartphone camera. The whole process takes barely five to ten minutes.
Ready to grab your lifetime free IDFC card?
Apply for IDFC First Bank Credit Card Takes 5 mins • 100% Paperless Video KYC
Whether you are grabbing the WOW card to finally start building your CIBIL score from scratch, or you are aiming for the Wealth card to enjoy those complimentary airport spa visits, IDFC has built a lineup that genuinely respects the customer's wallet. In a market obsessed with hidden fees, a truly lifetime free card with solid utility is a rare find.