












Understanding Credit Scores: A Beginner's Guide
Are you one of the many individuals who have heard of credit scores but are not quite sure what they mean or how they work?
If so, you're not alone.
Credit scores can seem like a mysterious and complex topic, but they play a significant role in our financial lives.
In this blog post, we'll delve into the world of credit scores, exploring what they are, how they're calculated, and why they matter.
What is a Credit Score?
A credit score is a three-digit number that represents your creditworthiness.
It's a way for lenders to assess the likelihood of you repaying your debts on time.
Credit scores are calculated based on information in your credit report, which is a record of your credit history.
This history includes information about your past loans, credit cards, and other debt obligations, as well as your payment history and any negative marks such as late payments or bankruptcies.
How are Credit Scores Calculated?
Credit scores are calculated using a complex algorithm that takes into account several factors.
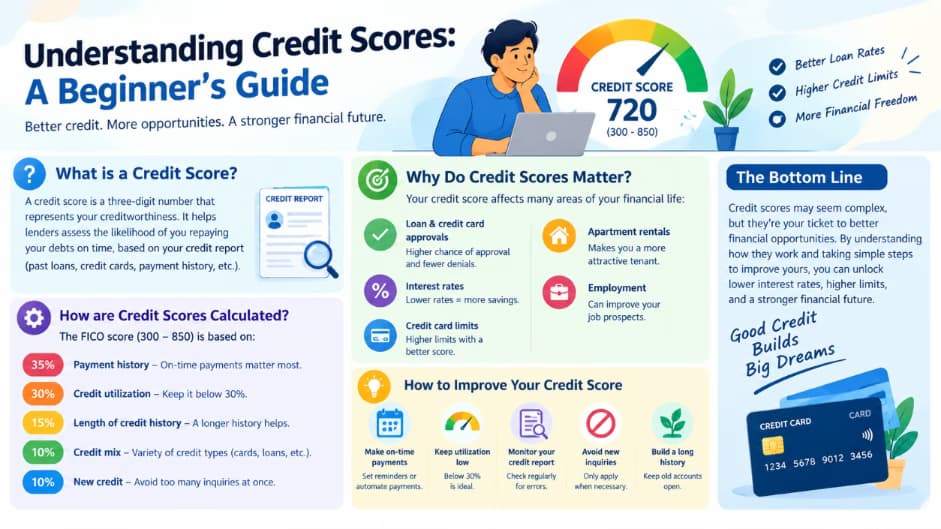
The most widely used credit score is the FICO score, which ranges from 300 to 850.
The factors that influence your FICO score include:
* Payment history (35%): This is the most important factor in determining your credit score.
A history of on-time payments will positively impact your score, while late payments will negatively affect it.
* Credit utilization (30%): This refers to the amount of credit you're using compared to the amount of credit available to you.
Keeping your credit utilization ratio low will help improve your credit score.
* Length of credit history (15%): A longer credit history will generally positively impact your score, as it shows that you have a track record of managing credit responsibly.
* Credit mix (10%): This refers to the variety of credit types you have, such as credit cards, loans, and mortgages.
A diverse mix of credit will help improve your score.
* New credit (10%): This factor takes into account any new credit accounts you've opened recently, as well as any inquiries into your credit report.
Applying for too much credit at once can negatively impact your score.
Why Do Credit Scores Matter?
Your credit score plays a significant role in your financial life.
It can affect your ability to get approved for loans and credit cards, as well as the interest rates you'll qualify for.
A good credit score can save you thousands of dollars in interest payments over the life of a loan.
Here are some ways your credit score can impact you:
* Loan and credit card approvals: A good credit score will increase your chances of getting approved for loans and credit cards.
A poor credit score may lead to denials or higher interest rates.
* Interest rates: Your credit score will influence the interest rates you'll qualify for.
A good credit score can help you qualify for lower interest rates, which can save you money over time.
* Credit card limits: Your credit score may also affect the credit limits you're offered.
A good credit score can result in higher credit limits.
* Apartment rentals: Some landlords may check your credit score as part of the rental application process.
A good credit score can make you a more attractive tenant.
* Employment: In some cases, employers may check your credit score as part of the hiring process.
A good credit score can make you a more attractive candidate.
How to Improve Your Credit Score
If you're looking to improve your credit score, here are some tips to get you started:
* Make on-time payments: Payment history is the most important factor in determining your credit score.
Set up payment reminders or automate your payments to ensure you never miss a payment.
* Keep credit utilization low: Keep your credit utilization ratio below 30%.
This will show lenders that you can manage your credit responsibly.
* Monitor your credit report: Check your credit report regularly to ensure it's accurate and up-to-date.
Dispute any errors you find.
* Avoid new credit inquiries: Applying for too much credit at once can negatively impact your score.
Only apply for credit when necessary.
* Build a long credit history: A longer credit history will generally positively impact your score.
Consider keeping old accounts open to show a longer credit history.
Conclusion
Understanding credit scores is an essential part of managing your financial health.
By knowing how credit scores work and taking steps to improve yours, you can unlock better loan and credit card offers, lower interest rates, and a stronger financial future.
Remember to always monitor your credit report, make on-time payments, and keep your credit utilization ratio low.
With time and effort, you can achieve a good credit score and enjoy the many benefits that come with it.