CardsGurujiCompare · Choose · SaveCheck all categoriesCheck all issuers
⌘K
Card Categories
Pick a card that matches how you actually spend.
Card Issuers
Explore cards from India's leading banks.
You're browsing page 22 of our complete credit card directory. Every card listed here has been reviewed by the CardsGuruji editorial team for fee accuracy, reward-rate correctness, and current offer validity. Listings are updated within 48 hours of any bank announcement. If a card on this page catches your eye, use the Compare feature to benchmark it against your current card before applying.
Cards on Page 22 — Annual-fee figures may be post-waiver. Always verify on the issuing bank's website before applying.
| # | Card Name | Bank | Annual Fee | Joining Fee | Rating |
|---|---|---|---|---|---|
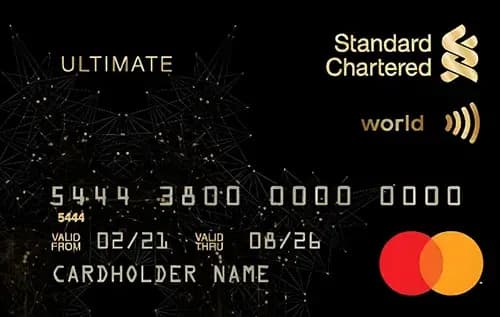
| 1 | Standard Chartered Ultimate | Standard Chartered | ₹ 5,000 | — | — |
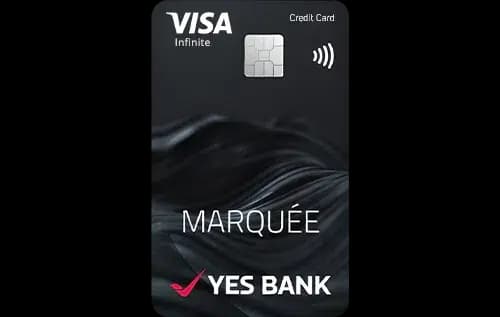
| 2 | Yes Marquee | Yes Bank | ₹ 9,999 | — | — |
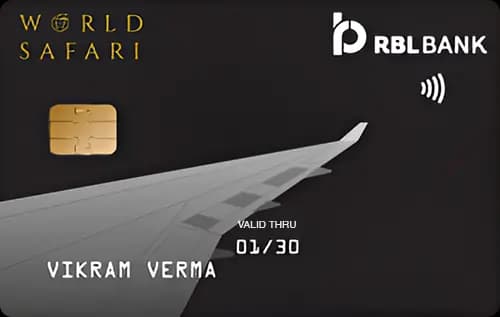
| 3 | RBL Bank World Safari | RBL Bank | ₹ 3,000 | — | — |
| 4 | IndusInd Legend | IndusInd Bank | Lifetime Free | — | — |
| 5 | Kotak League Platinum Credit Card | Kotak Mahindra Bank | ₹ 499 | — | — |
| 6 | Kotak White Credit Card | Kotak Mahindra Bank | ₹ 3,000 | — | — |
Explore head-to-head comparisons for niche, regional, and secured credit cards.
If you are exploring cards further in our directory, many products cater to specific banking relationships, regional bank customers, or secured cardholders. Using a secured card for 6 to 12 months with disciplined on-time payments establishes a strong credit profile, making you eligible for premium unsecured credit cards.
Practical answers regarding secured cards against fixed deposits, CIBIL score repair, and approval requirements.
A secured credit card is backed by a fixed deposit held with the issuer. The issuer sets the deposit and credit-limit terms and still evaluates applications under its own criteria; collateral does not guarantee approval. Check the issuer's current requirements before applying.
Building a brand-new credit score from scratch (starting from a 'NH' or -1 status) takes approximately 6 months of active credit card usage. Repairing a damaged credit score (raising it from below 600 to 750+) typically requires 12 to 18 months of disciplined on-time payments, maintaining a Credit Utilization Ratio below 30%, and clearing all past overdue balances.
Yes. Individuals without salary slips or ITR records can easily access credit cards through two primary options: (1) Applying for an FD-backed secured card (such as Kotak 811 Dream Different, SBI Unnati, or IDFC FIRST WOW), or (2) Requesting an add-on credit card linked to an earning family member's existing credit card account.
The Total Amount Due is the entire balance billed for your billing cycle; paying this in full ensures you incur zero interest. The Minimum Amount Due (MAD) is typically 5% of the total balance; paying MAD keeps your account active and avoids late payment fees, but the remaining 95% incurs steep revolving interest charges (3.5% per month or 42%+ per annum) from the transaction date. Paying only the minimum is a common debt trap.
You can increase your credit limit by: (1) Maintaining flawless on-time bill payments for 6 consecutive months, (2) Submitting updated income proofs (recent salary hikes or higher ITR records) through your net banking portal, (3) Keeping credit card utilization below 30%, and (4) Accepting pre-approved credit limit enhancement offers regularly sent via SMS or mobile banking apps.
Credit Utilization Ratio (CUR) is the percentage of your total sanctioned credit limit you use in a billing cycle. If your total credit limit is ₹1,00,000 and your statement balance is ₹30,000, your CUR is 30%. Credit bureaus consider CUR heavily (approx. 30% of your score weight). Maintaining a CUR below 30% signals responsible financial management, whereas high utilization (above 50%) depresses your CIBIL score.
If your application is rejected: (1) Check the formal rejection reason from the bank (often low CIBIL, address mismatch, or high debt-to-income ratio), (2) Download your free credit report to verify there are no inaccurate overdue records, (3) Avoid applying to other banks immediately as multiple rejections compound credit damage, and (4) Wait 3 to 6 months while building credit with an FD-backed card before re-applying.
An add-on credit card is a secondary card issued to family members (parents, spouse, siblings, or children above 18 years) linked to the primary account holder's credit line. The primary cardholder can set custom monthly spend limits for each add-on card, all transactions appear on a single consolidated statement, and all rewards pool into the primary account.
Yes. After 12 to 18 months of disciplined on-time bill payments on your secured card, your CIBIL score will typically rise to 750+. At that stage, you can contact the issuing bank to request an upgrade to an unsecured card based on your updated credit score and income, allowing the bank to release and unpledge your original fixed deposit.
When you initiate a credit card cancellation request, any remaining unredeemed reward points are forfeited immediately upon account closure. To avoid losing value, redeem all points for brand gift vouchers, flight bookings, or statement credit before formally submitting your card cancellation request to customer care.